By God’spower Ede, Lafia.
Over 3 million Nigerians are estimated to have lost billions of naira to a recent Ponzi scheme operating under the name National Reading Culture, NRC — a platform that promised huge returns for “promoting reading culture” but collapsed within months.
The scheme has left families devastated, triggering fresh debate about financial literacy, regulation, and Nigeria’s obsession with “quick money.”
NRC presented itself as a digital initiative to promote reading in Nigeria.
However, participants were told to register online, pay membership/activation fees ranging from ₦5,000 to ₦50,000, and then “earn” daily or weekly returns by referring others and completing simple reading tasks.
Packages include;
1. ₦5,000 – Basic package
2. ₦10,000 – Silver package
3. ₦20,000 – Golden package
4. ₦50,000 – Diamond/VIP package.
The model relied on two classic Ponzi hallmarks, namely:
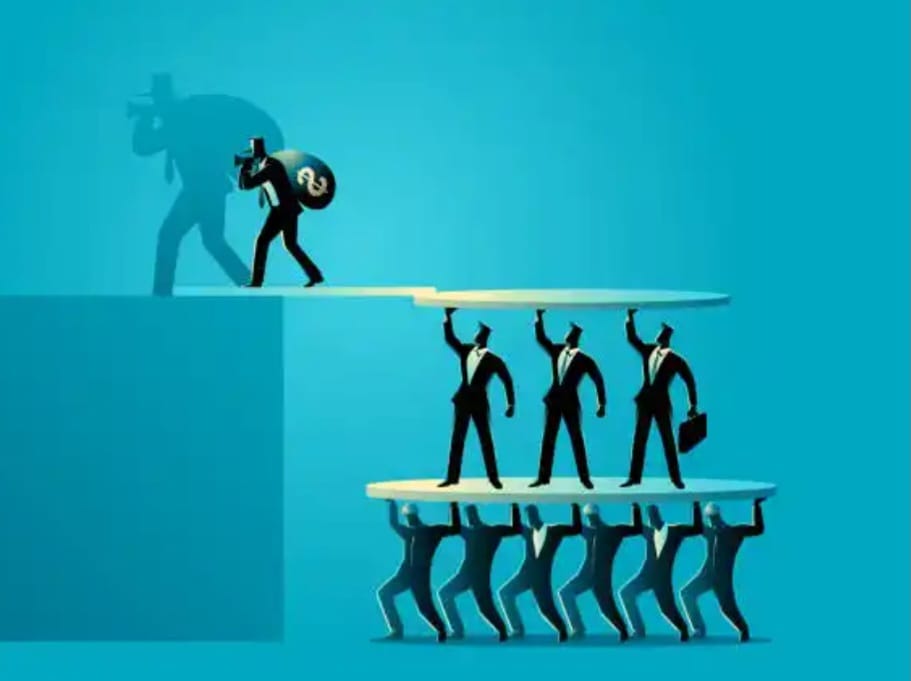
Recruitment-driven income: The bulk of earnings came not from reading, but from bringing in new members. Early investors were paid with money from new entrants.
Unrealistic Return on Investment- ROI: Promoters advertised returns of 30% to 100% within 30 days, far above any legitimate investment rate.
Initially, payments were made via bank transfers and crypto wallets for the first 6-8 weeks to build trust. Then withdrawals were later delayed, then the website went offline, and the operators disappeared.
Unfortunately, this is not Nigeria’s first brush with Ponzi schemes. From Mavrodi Mundial Movement, MMM, in 2016, to Twinkas, Get Help Worldwide, Ultimate Cycler, iCharity, and MBA Forex, among others, Nigerians have lost hundreds of billions over the last decade.
Yet data from victims’ groups and financial analysts estimate that over 3 million people joined NRC.
Victims include University students, civil servants, health workers, bankers, traders, and even retirees. Many invested their salaries, business capital, and borrowed funds, hoping to “double it fast.”
Sadly, financial experts and sociologists attribute this mad rush to patronising ponzi schemes Economic Hardship: with inflation above 30% and unemployment high, many Nigerians see Ponzi schemes as a shortcut out of poverty.
Another factor is financial Illiteracy: Lack of understanding of how investments work makes unrealistic returns look plausible.
Social Proof & Hype: including testimonials on TikTok, WhatsApp, and Facebook showing fake “payment alerts” created FOMO — Fear of Missing Out.
There is also a Trust Deficit in Legitimate Systems as slow returns from banks, stocks, and agriculture push people toward schemes promising instant wealth.
Lastly, the “Get-Rich-Quick” Culture that encourages the societal celebration of sudden wealth, regardless of source, normalizes the risky ventures.
This development has continued to have negative implications for both the national economy and the psychological well-being of victims.
This is because billions of naira were moved out of productive sectors into a scheme that created no goods or services. It drains household savings, reduces consumer spending, and weakens trust in digital finance platforms.
Socially and health-wise, there are reported cases of depression, anxiety, broken marriages, and, in some cases, suicide attempts by victims.
Many families lost school fees and medical funds. The psychological toll is most severe among youths who took loans to invest.
Therefore, the recent development should teach many Nigerians that no legitimate investment guarantees 100% returns in 30 days.
Accordingly, people should endeavour to verify with the Securities and Exchange Commission, SEC, the Central Bank of Nigeria, CBN, and the Corporate Affairs Commission, CAC, before getting involved with such online investment platforms. Unfortunately, NRC was not registered as an investment firm.
It must also be noted that real businesses generate profit from products or services, not from recruiting new people, while genuine wealth takes time, discipline, and financial education.
Thus, to avoid a repeat, Nigerians must reject the “quick money” syndrome and embrace financial literacy.
Government agencies must intensify public enlightenment, while schools should teach personal finance from the secondary level.
As one victim in Jos, Plateau State, put it: “We were chasing millions and lost our thousands. Reading should build the mind, not bankrupt it.”
In conclusion, until the culture shifts from chasing miracles to building value, Ponzi schemes will keep finding willing participants in Nigeria.